Understanding Support at Home contributions gives you the power to make the best choices for your care and budget. While self-funded retirees contribute more for some services, clinical care remains fully funded for everyone. Knowing how provider fees work helps you get the most out of your funding.
Key Takeaways
- Clinical care services like nursing and physiotherapy attract no contribution regardless of your financial position.
- Means-tested contributions apply to independence services and everyday living services.
- Your contribution percentage applies directly to the provider’s specific hourly rate.
- Minimum visit times can significantly increase your out-of-pocket costs for care.
- Purchasing everyday living services privately can sometimes be more cost-effective.
Why Do Self-Funded Retirees Pay More?
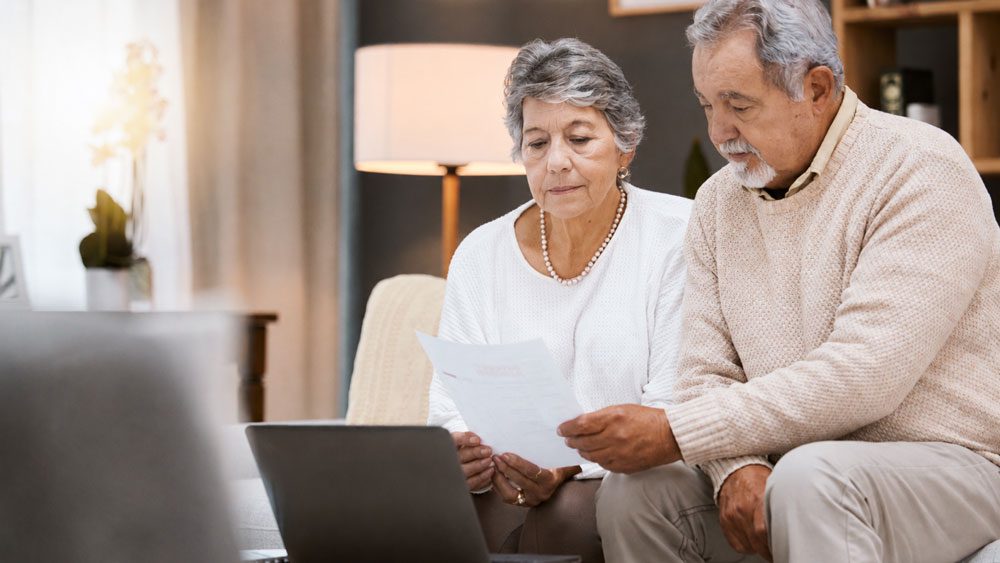
A big frustration for self-funded retirees under Support at Home is seeing other people receive the same government-funded services while paying less for them. It can feel unfair, particularly if you have spent your working life saving and investing for retirement.
But the new system is deliberately designed to make people with greater financial means contribute more towards the cost of their care. The key is understanding how the Support at Home contributions work.
For a broader overview of aged care costs, fees and government support, see our Aged Care Funding Guide.
How Are Support at Home Contributions Calculated?
The Support at Home Program provides funding based on your assessed care needs, with annual funding ranging from around $11,000 to $78,000. The amount you contribute depends not only on your financial position but also on the type of service you receive.
There are three Support at Home service categories: clinical care, independence and everyday living.
Clinical care is different. Services such as nursing, personal care and allied health attract no contribution, regardless of whether you are a full pensioner, part pensioner or self-funded retiree. The means-tested contributions are only applied to independence and everyday living services.
Independence services include transport and social support, and attract a contribution of up to 50 per cent. While everyday living services include cleaning, gardening and shopping assistance, these have the highest contribution rate of up to 80 per cent.
It is important to understand that the percentage is applied to the provider’s price for the service. You need to consider the contribution rate and the service price together.
How Provider Prices Impact Your Final Cost
Suppose a provider charges $100 an hour for a service that falls into the independence category. A person paying a 50 per cent contribution would pay $50 an hour. But if another provider charges $130 an hour, that same 50 per cent contribution would equate to $65 an hour. The contribution rate hasn’t changed, but the amount coming out of your pocket has.
There can be an even bigger difference when minimum visit times are involved. Let’s say you need an hour of social support. One provider might charge $100 an hour, making your 50 per cent contribution $50. While another provider might charge $85 an hour, costing you $42.50 an hour. That sounds cheaper until you discover the provider has a two-hour minimum visit. You could end up paying $85 for the same amount of care.
When to Consider Private Services
When it comes to everyday living services you really need to consider if it’s better to buy the services privately. If a Support at Home provider charges $105 an hour for cleaning, an 80 per cent contribution means you pay $84 an hour. A private cleaner might charge around $50 an hour. The government funded service actually costs you considerably more.
This is one of the traps for self-funded retirees. The percentage tells you how much of the provider’s price you contribute, but it doesn’t tell you what the service will actually cost. That’s why you need to look at them in combination.
What to Check Before Choosing a Provider
Rather than simply choosing a provider because it has a lower published hourly rate make sure you have a clear idea of the services you want and consider when you want the services delivered. Most providers charge more outside standard hours, but how much more varies widely. And make sure you check minimum visit times; a lower hourly price can quickly become a more expensive contribution if you are required to pay for more care than you need.
For self-funded retirees, paying a higher contribution does not mean Support at Home provides no value. Clinical care can be particularly valuable because there is no co-contribution regardless of your financial position. For other services, however, you need to do the sums.
The important question isn’t simply “What percentage do I have to pay?”
It is “What will this service actually cost me, and would I be better off buying it privately?”
Whenever someone gives you a percentage, ask: “Of what?” Then crunch the numbers.
Ready to Find Support at Home?
Once you understand your likely costs, the next step is finding a provider that can start services when you need them.
Aged Care Decisions is Australia’s largest free aged care placement and support service. We help older Australians and families find suitable Support at Home providers without the usual calls and follow-ups.
Your dedicated specialist will discuss your needs and prepare a tailored Options Report. We can contact suitable providers, arrange introductions and support you through the onboarding process.
Our service is free and independent. Get started with Aged Care Decisions today.
FAQs
Do self-funded retirees pay for clinical care under Support at Home?
No, self-funded retirees do not pay a contribution for clinical care. Services such as nursing and physiotherapy are fully funded by the government for everyone. Your financial position does not change this.
Which Support at Home services require a contribution?
You will need to pay a means-tested contribution for independence and everyday living services. Independence services like transport have a contribution of up to 50 per cent. Everyday living services like cleaning have a contribution of up to 80 per cent.
How does a provider’s hourly rate affect my contribution?
Your contribution percentage applies directly to the provider’s hourly rate. If a provider charges a higher hourly rate, your out-of-pocket cost will be higher even though your percentage stays the same. Always check the provider’s price list.
Why do minimum visit times matter for my budget?
Minimum visit times matter because they can force you to pay for more care than you actually need. A provider with a cheap hourly rate but a two-hour minimum visit might end up costing you more overall.
Should I buy everyday living services privately instead?
Yes, it can sometimes be cheaper to buy everyday living services privately. Because the government contribution for things like cleaning can be up to 80 per cent, a private cleaner might charge less per hour than your out-of-pocket Support at Home cost.
The information contained in this article is intended as general information only and does not constitute personal financial advice, legal advice or professional advice. While care has been taken to ensure the information is accurate and up to date at the time of publication, rules, rates and circumstances can change.